
 This week’s WARC Media Global Ad Spend Forecast Q3 2026 update global adspend is forecast to grow 11.9% to reach $1.34trn (£1.02trn) this year, despite consumer caution.
While AI is driving the increase, social media, search and retail media are three of the biggest channels for ad investment; together they are expected to account for 66.4% of total global ad spend in 2026, rising to 70.0% in 2028.
Meanwhile, video on-demand (15.1% to $48.4bn), retail media (14.3% to $202.1bn), search (14.2% to $295.7bn) and digital OOH (13.7% to $21.7bn) will also see double-digit increases this year.
The report draws its own conclusions, but Decision Marketing asks leading industry professionals for their take and finds that, while AI appears to be king, in this new era, getting the best marketing intelligence is just as crucial.
First up is Brave regional vice president EMEA Andy Squire, who believes the study reinforces why search continues to attract investment.
He explains: “When advertisers are under pressure to make budgets work harder, knowing what people are actively looking for gives you a much stronger signal than relying on what they did weeks or months ago.
“What is changing is where that intent shows up. Consumers are searching across traditional engines, AI tools and other discovery environments, so advertisers need to follow the behaviour rather than default to the same platforms. The opportunity is to respond to demand as it emerges and use those signals to reach genuinely incremental audiences, rather than continually paying more to compete for the same users.”
Even so, Preciso chief executive Piero Pavone, says that while the forecast is positive for the industry, stronger adspend also means more competition for attention.
He adds: “Growth alone won’t make campaigns more effective. For advertisers, the priority has to be using that investment more intelligently. Consumer behaviour can change quickly, so marketers need to understand which audiences, impressions and moments are genuinely valuable as demand shifts.
“Real-time signals can help adjust bidding and targeting accordingly, moving spend towards the opportunities most likely to deliver value. In a market where budgets are growing but consumers remain cautious, efficiency will matter just as much as scale.
Over at Limelight, co-founder and chief revenue officer James Macdonald reckons that while the forecast shows plenty of growth in advertising, it also highlights just how concentrated that spend remains, with a very large share sitting within a handful of major platforms.
He continues: “For the rest of the ecosystem, that makes the question of control increasingly important. We’re seeing more businesses look closely at how much of their media operation they actually control, from the technology they use to the partners and supply and demand relationships behind it.
“The aim isn’t to rebuild everything in-house, but to have the flexibility to choose how you operate and who you work with. As the market grows, that independence becomes increasingly valuable.”
Meanwhile, Parallel managing director UK Ben Dimond warns that, with advertisers continuing to put more money into digital media, the cost of getting relevance wrong also increases.
He explains: “More investment and more automation won’t help if the placements being bought for that creative, don’t drive lift.
“The next step for AI in media should be about improving that fit by understanding human behaviour, not just making buying faster. Advertisers need to understand how a specific creative will resonate within a specific piece of content for the customer And doing this will drive better outcomes.
“As budgets grow, using AI to test those combinations at scale can help brands make smarter placement decisions, waste less budget and get drive better outcomes from their media investment.”
VIOOH global field marketing director Diu Hoang says the forecast confirms what her company has seen this year: that there is a real inflection point in the adoption of digital out-of-home.
She adds: DOOH is no longer planned as a bolt-on or afterthought, but as a core channel in the media mix. This double-digit rise positions the medium alongside established stalwarts – social, retail media and search – and programmatic is central to that momentum.
“Advertisers want the scale and brand safety of premium public screens, bought with the same precision and flexibility they expect from other digital channels. Programmatic DOOH delivers that, from data-driven audience targeting and dynamic creative to curated deals, all of which we’re scaling across VIOOH.
“Perceptions are shifting too – DOOH is no longer seen as a branding-only channel. With programmatic in the mix, advertisers know that it can directly drive performance (footfall, sales). With everything the channel offers, it’s no wonder why DOOH is becoming a mainstay of the media mix, and programmatic will only accelerate that.”
However, Wingify VP of marketing John Hughes reckons that as budgets rise, so will scrutiny over whether that spend is actually delivering.
He continues: “For marketers, the job doesn’t end when someone clicks. They need to understand what happens once people arrive, where journeys break down and why interest fails to convert. AI is also changing the path to purchase, with more research happening before a consumer reaches a brand’s site.
“That makes each visit more valuable. The brands that connect media performance with what happens next will be in the strongest position to turn higher spend into better business outcomes.”
For Nutcake chief executive Tim Mitchell it is no surprise that social comes out as the fastest growing channel, with brands starting to get their heads round social disciplines and increasingly investing in content creation, whether for owned channels or investing more in creator marketing.
Mitchell explains: “We can see a big appetite from brands to start buying more social insights and AI-enriched data so they can develop more sophisticated content strategies, which bodes well for future growth in social over the next few years.
“AI now feels like the area most advertisers are competing on. The danger for brands is knowing exactly what they should be buying, in terms of putting together their media tech stacks and what data they feed into it to make those investment decisions in the next few years.
“We’ve focused on helping brands understand how their brand or product shows up in organic content, even when they’re not tagged or mentioned. If brands are to continue investing harder into content on social platforms, it’s vital they have the right information to make it effective.”
But the final word goes to esbconnect chief executive Suzanna Chaplin. She says: “An 11.9% rise in global adspend sounds like great news, but more money in the market doesn’t automatically mean better returns. With social, search and retail media expected to account for around two-thirds of spend this year, brands risk paying more to compete for the same attention in increasingly crowded places.
“That’s why diversification matters. Marketers should be asking where they can find genuinely new audiences, build first-party relationships and collect data they actually own. That might mean testing newer opportunities, but it also means not overlooking proven routes such as email. The opportunity is to use bigger budgets to broaden the mix, rather than simply spend more in the same places.”
It seems that while US president Donald Trump asserts that AI should be rebranded, there is definitely a place for “super intelligence” in marketing…
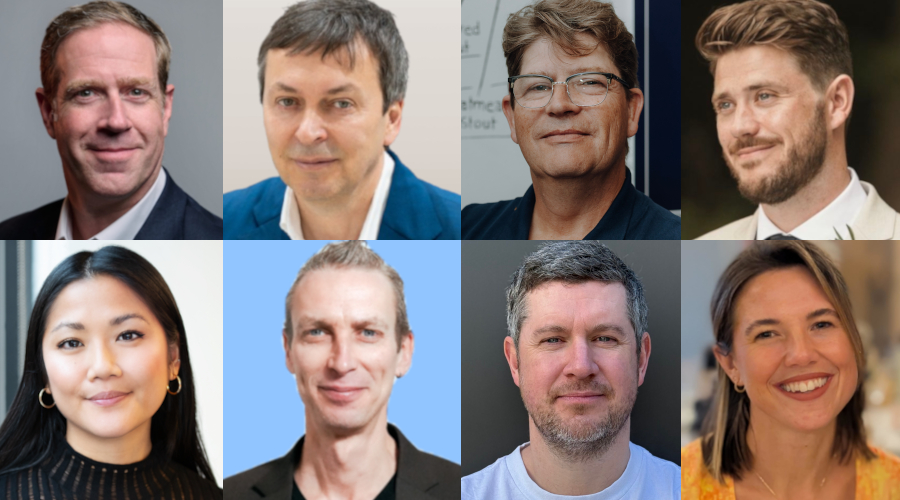
Clockwise from top left: Andy Squire, Piero Pavone, James Macdonald, Ben Dimond, Diu Hoang, John Hughes, Tim Mitchell, Suzanna Chaplin
Related stories
Global adspend to hit $1.34trn as AI goes gangbusters
H1 digital spend tops £21bn as retail and video clean up
IAB UK: Govt must act so digital sector can top £242bn
AI-driven advertising spend set to reach £18bn by 2030
Rise of agentic web ‘demands major marketing rethink’
Creator economy to top £1bn in 2026 as sector matures
Crisis? What crisis? UK the powerhouse as digital soars
Be the first to comment on "WARC adspend forecast: The era of ‘super intelligence’"